

A changing conversation
For three years the market debated how fast rates would come down. In one speech at Jackson Hole, new Chair Kevin Warsh changed the conversation to whether, and how quickly, they might go back up. In his first address as Chair, he said the Fed’s “predominant focus right now should be on prices” and reaffirmed the 2% inflation target. Odds of a rate increase at the September meeting jumped from 35% to 57% in a single session, and Treasury Yields finished the month near their highs for the year.
Chair Warsh has reason for concern. Core PCE held at 3.3% in July and headline PCE at 3.7%, both drifting the wrong way, with energy up 14.7% year over year and shelter driving two-thirds of the monthly CPI increase. Meanwhile the labor market cracked: July payrolls fell 23,000, revisions erased another 103,000 jobs from May and June, and the 4.1% unemployment rate is flattered by a labor force participation rate of 61.4%, a level unseen outside the pandemic. Wage growth of 3.2% now runs below inflation. The graphic below illustrates the Fed’s conundrum1.
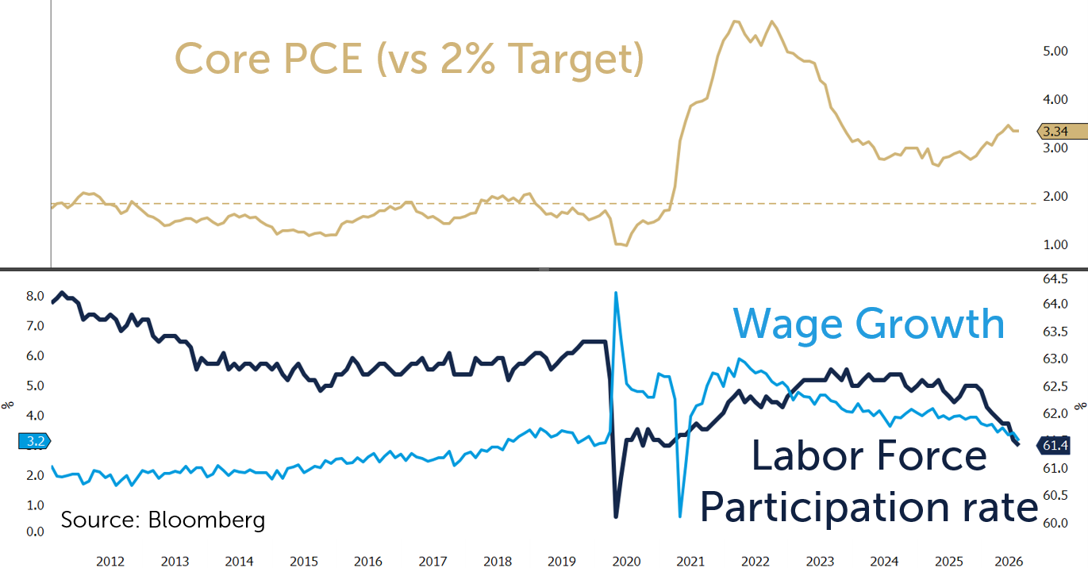
Markets shrugged. The S&P 500 set a new all-time high early in the month before pulling back modestly. That is the tension heading into September: inflation rising, the workforce shrinking, and risk appetite (arguably) not pricing either scenario appropriately.
Before we review our Navigator process, let’s review August’s market performance.
August Market Review
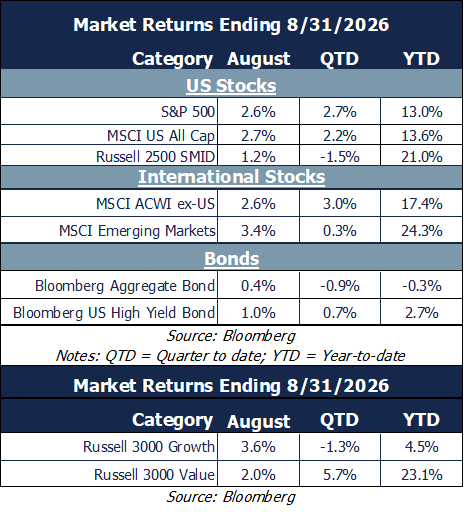
August was broadly positive across risk assets:
- Emerging Markets led, followed by growth stocks, with the S&P 500 and international developed markets solidly in positive territory.
- Leadership for the year sits beyond the US large-cap space. Both emerging markets and SMID (small and mid-cap) stocks far outpace the S&P 500’s 13.0% YTD gain.
- Value stocks still dominate performance this year, ahead by 20 percentage points despite growth’s August resurgence.
- Bonds made slight gains this month, but remain a performance drag as inflation concerns remain front and center.
Market leadership was concentrated in cyclical sectors in August, reflecting geopolitical concerns as well as AI-driven momentum:
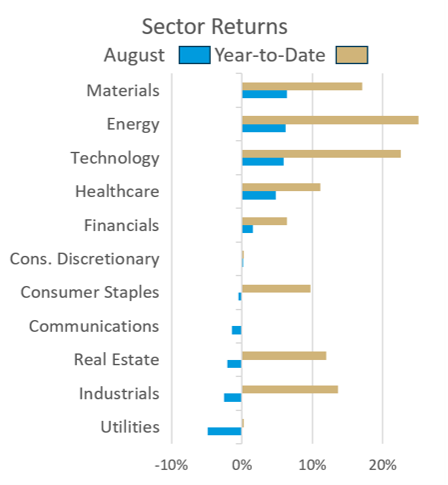
- Materials, Energy and Technology each gained roughly 6% for the month; those sectors did much of the work, with healthcare just behind.
- Sector breadth was mixed: Six of eleven sectors finished positive, but the contribution fell off sharply after the top four sectors.
- Rate-sensitive and defensive sectors lagged. Utilities was the clear laggard at roughly -5%, with Industrials, Real Estate and Communications each down 1% to 2%, and Consumer Staples slightly negative.
- While performance has been broad, energy-related and technology sectors continued their strong YTD leadership as AI and energy themes dominate.
Our Navigator framework informs us of our outlook.
September 2026 Navigator Outlook
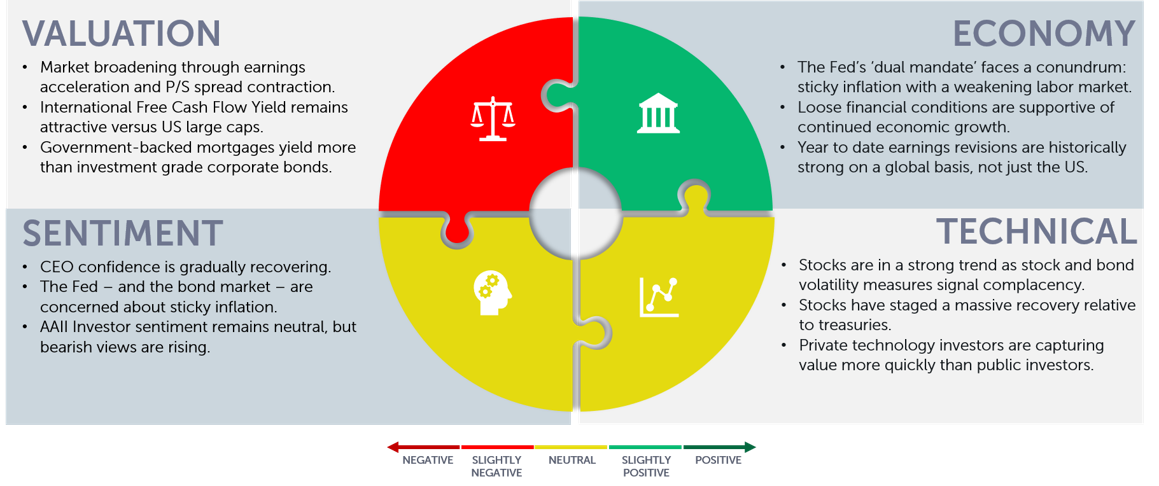
Economy: Sticky inflation alongside a weakening labor market leaves the Fed’s two mandates pulling in opposite directions, and the new Chair has said which comes first. Offsetting that, financial conditions remain loose and supportive of growth while earnings revisions have been historically strong both in the US and across the globe.
Technicals: Stocks hold a strong trend above the 200-day moving average, but subdued stock and bond volatility readings mean little downside is priced into stock2. Meanwhile, rolling 10-year stock-minus-bond returns sit at the high end of their range3, suggesting potential reversion. Finally, private investors are capturing technology value before IPO, suggesting lower margin of safety for public market investors.
Sentiment: CEO confidence is recovering from post-COVID lows, a genuine forward-looking positive4. The bond market is responding to inflation worries by holding the 10-year and 30-year far above their September 2024 levels despite Fed cuts in between5. AAII retail sentiment is neutral, with bearish views rising.
Valuation: The cap-weight to equal-weight P/E spread has narrowed from 5 points last October to 2.6 points today, and it narrowed the healthy way, through earnings catch-up rather than price declines. International stocks remain attractive as their free cash flow yield is significantly higher than that of the S&P 500. Government-backed mortgages now yield more than BBB corporates, reducing the need to take on credit risk6.
Outlook and Recommendations: Fragile: handle earnings with care
Stocks appear to be in a good place. Volatility is low, the trend is strong, and the markets are supported by the strongest earnings growth in years. Forward earnings are being revised higher: up 26% for the S&P 500, 30% for non-US Stocks, and more than 60% for emerging market stocks7. Prices have followed profits up this year, a far healthier foundation than the valuation-driven gains of 2023 and 2024. The fundamentals look sound.
Our concern is the backdrop: the support underneath this market may be thinner than it appears, and markets have a way of testing the fundamental strength.
In August a new Fed Chair reframed policy around the inflation fight, while slowing wage growth and a lower participation rate highlight weakness in the labor market. Investors now must confront conflicting realities: earnings are strong, but the cost of capital is likely rising at a time when the consumer may weaken.
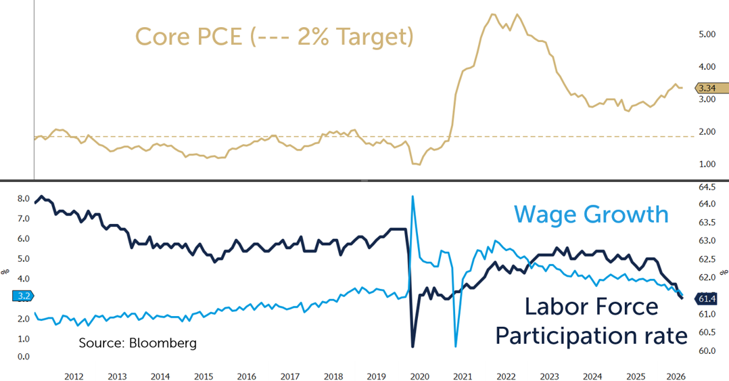
Four things shape our thinking about fragility and protection for the rest of 2026: Inflation, Fed Policy, Valuations and Earnings.
Inflation matters, and the source of it matters greatly. High energy prices, a result of the Iran war, continue to flow through the economy. Once the war is over, inflation can hopefully resume its path downward.
The policy error risk is real. Chair Warsh has reason to prioritize the inflation fight. But he will be raising rates8 into a weakening labor market, with the low unemployment helped by low labor force participation. If he moves too fast, the labor data worsens; too slow and inflation may get out of hand. We are skeptical of anyone who is certain about how this resolves, and we seek to build a portfolio that does not require us to be right.
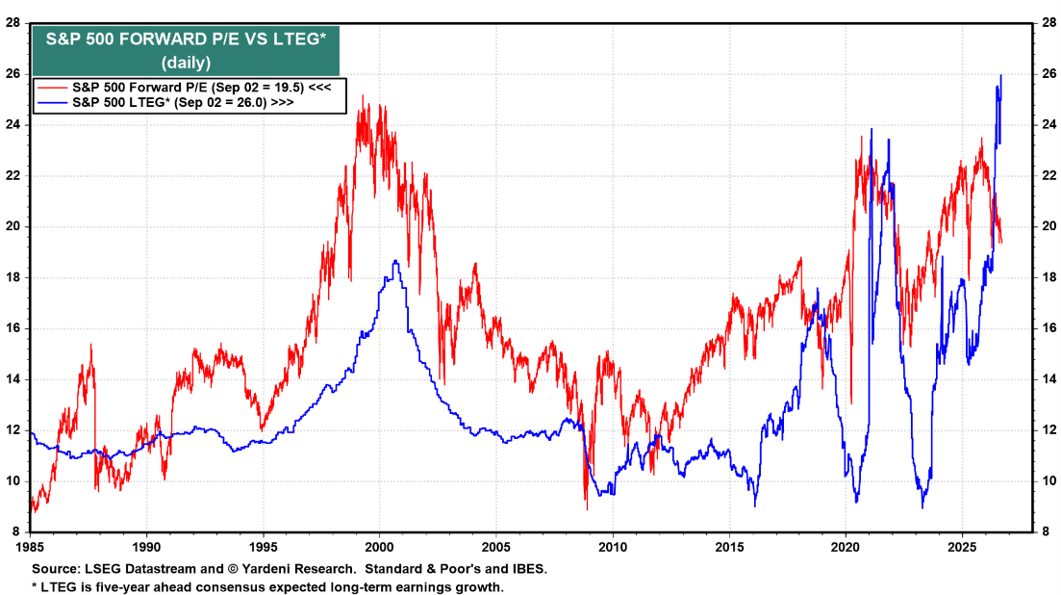
Valuations for US Stocks (see the above chart9) have come down from their highest levels as earnings have surpassed forecasts this year. These lower valuations, however, still leave less cushion than long-term history would suggest is normal. At the same time, expectations for continued earnings growth are as high as they have ever been, and that is the rub. A failure to meet these expectations may cause a sharp pullback in stocks.
The changing dynamics since COVID and the advent of AI do offer opportunity. While the S&P 500 offers a 2.89% free cash flow yield – close to its lowest in a decade as companies spend lavishly on the AI buildout – international stocks yield 4.42%, offering a higher margin of safety despite lower growth10. Compensation for taking risk in the US has narrowed, while opportunity remains beyond our borders. High starting valuations do not cause declines, but they remove some of the cushion when something else does.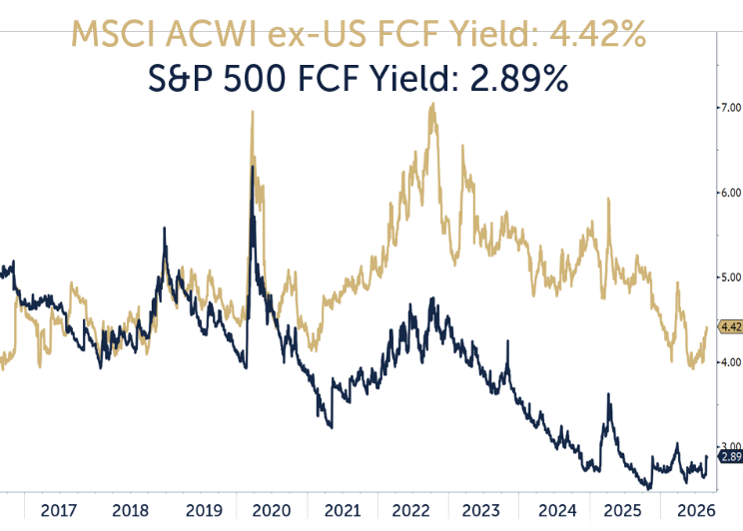
Fragile does not mean broken, and it does not mean you should head to the sidelines. It means that you should build your portfolio with great care. The positioning suggestions that follows are designed to help portfolios participate in strong earnings without depending on them, because the cost of being wrong has risen faster than the reward for being right.
Portfolio Construction and Positioning
Our Navigator process helps guide our portfolio construction, reflecting the broadly supportive, yet fragile, economic outlook. Our portfolio is focused on the following:
- Mid-cap and international equities: These segments continue to offer attractive valuations relative to U.S. large caps, and the market is beginning to recognize their potential. The forward P/E spread between the S&P 500 and its equal-weight counterpart has narrowed; the outlook suggests further broadening of returns.
- Balanced exposure across styles: We maintain a mix of growth and value stocks positioned for a broadening that is now developing. If the Fed follows through with rate hikes, the discount applied to long-duration growth earnings is likely to rise, which makes the balance a hedge as much as a preference.
- Fixed income remains compelling: Bond yields exceed the dividend yield of large-cap equities, and real (inflation-adjusted) yields are positive, supporting the case for continued fixed income exposure.
- Mortgage-backed securities: Government-backed mortgages currently yield more than BBB corporate bonds, compensating investors better for taking no credit risk. That spread relationship makes the case for portfolio risk management; selectivity in corporate bonds is crucial, while the government-backed mortgage market offers compelling opportunity.
- Alternative investments: Bonds have cushioned equity declines when inflation was low and falling. When inflation drives markets, stocks and bonds tend to fall together, as 2022 demonstrated. Non-correlated assets may serve as crucial ballast in such an environment, and we continue to find meaningful opportunities in both non-correlated public strategies and private market investments that access return streams not tied to public market direction.
The market has shown remarkable resilience through a period of rising uncertainty, supported by solid economic performance and a broad acceleration in corporate earnings. But good news tends to compress the reward for taking risk; diversification and valuation discipline matter more now, not less. We counsel investors to stay invested, stay diversified, and keep their focus on long-term goals rather than the next headline.
This material is intended to be educational in nature, and not as a recommendation of any particular strategy, approach, product or concept for any particular advisor or client. These materials are not intended as any form of substitute for individualized investment advice. The discussion is general in nature, and therefore not intended to recommend or endorse any asset class, security, or technical aspect of any security for the purpose of allowing a reader to use the approach on their own. Before participating in any investment program or making any investment, clients as well as all other readers are encouraged to consult with their own professional advisers, including investment advisers and tax advisors. OneAscent can assist in determining a suitable investment approach for a given individual, which may or may not closely resemble the strategies outlined herein.11
1) Source: Bloomberg (All inflation and labor market data)
2) Source: Bloomberg
3) Source: Topdown Charts
4) Source: Conference Board
5) Source: Bloomberg
6) Source: Bloomberg
7) Source: Bloomberg: non-US stocks refer to the MSCI ACWI-Ex US, and Emerging markets refers to the MSCI Emerging Markets
8) Source: CME FedWatch – CME Group as of September 3, markets price greater than an 80% probability that the Fed will raise rates by the end of the year
9) Source: Yardeni Research
10) Source: Bloomberg
11) Source: Market Returns reference the following indices: Large Cap – S&P 500, Mid Cap Growth – Russell Midcap growth, Mid Cap Value – Russell Midcap Value, Small Cap – Russell 2000, Developed – MSCI EAFE, Emerging – MSCI Emerging Markets, Aggregate – Bloomberg US Aggregate, High Yield – Bloomberg High Yield
OAI01411