

Key Events: Pressure to hike rates intensified
August economic data reinforced expectations for a September Fed rate hike. Producer prices climbed 5.4% year-over-year while Core CPI increased 0.3% for the month, both topping forecasts.1 Odds of a rate hike jumped from 61.9% to 88.1% during the week.2 With hike odds this elevated, market focus has shifted from whether the Fed should raise rates to how much it must raise them to contain inflation.
Market review: Surging yields & oil prices expose risk
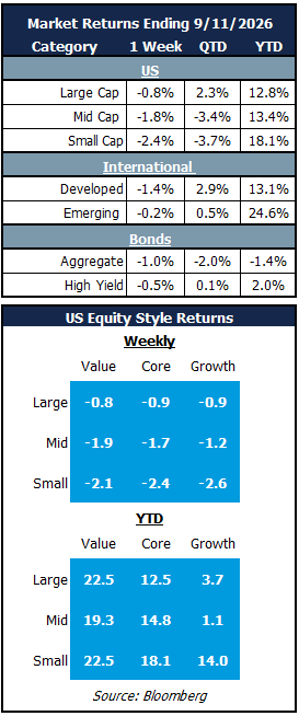
US crude oil rose more than $8 on the week to close just over $100, as dwindling reserves add to inflation concerns. The 10-year Treasury yield jumped 18 basis points to close the week at 4.97% challenging a two-decade high.3 Equities and fixed income fell as risks to the outlook mounted.
Outlook: Modest tightening expected for now
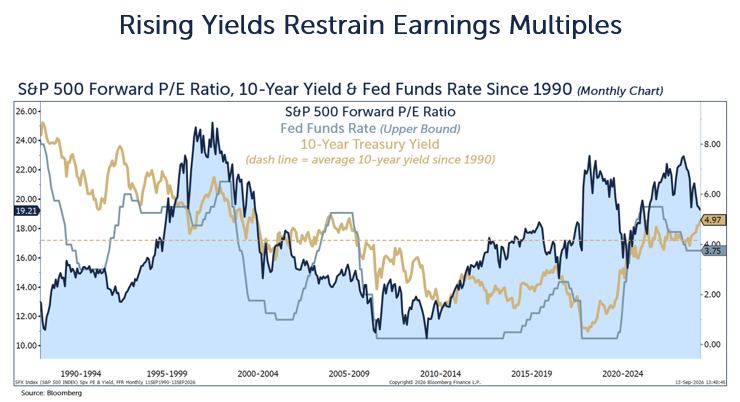
At the onset of 2026, Fed Funds Futures contracts were projecting two interest rate cuts by September. Expectations have completely reversed course, as futures contracts now anticipate 2 hikes by year-end.4 Rising oil prices, solid economic growth and extraordinary AI investment have lifted inflation expectations, and the bond market has responded with higher yields and a clear test for the new Fed Chair. Since the end of February, the 10-year US Treasury yield has risen over 100 basis points as shown in the chart below.
Equities typically struggle around rate hike cycles, but the market has already priced in some anticipated Fed tightening. The S&P forward P/E has declined from 22x at the start of the year to just over 19x today, adjusting the earnings yield (inverse of P/E) from 4.55% to 5.2%. Historically, changes in the Fed Funds Rate have taken many months to impact the economy and the rate of earnings growth. If the Fed can contain inflation with a one or two-hike mid-cycle adjustment, market valuations may have already discounted the changes ahead. Should inflation remain persistent into early 2027 and force the Fed to raise rates more aggressively, material risks to valuations and the earnings outlook could emerge.
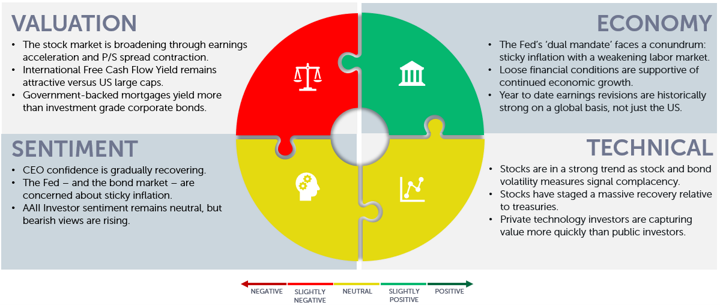
Investors would be wise to rebalance risk exposure back to targets, but remain diversified across asset classes, sectors, and geographies. With sharply rising oil prices, the bond market testing the Fed’s resolve and midterm elections now under two months away, the current choppiness in the outlook may give way to clearer sailing into year end.
OneAscent Navigator Outlook: September 2026
This material is intended to be educational in nature, and not as a recommendation of any particular strategy, approach, product or concept for any particular advisor or client. These materials are not intended as any form of substitute for individualized investment advice. The discussion is general in nature, and therefore not intended to recommend or endorse any asset class, security, or technical aspect of any security for the purpose of allowing a reader to use the approach on their own. Before participating in any investment program or making any investment, clients as well as all other readers are encouraged to consult with their own professional advisers, including investment advisers and tax advisors. OneAscent can assist in determining a suitable investment approach for a given individual, which may or may not closely resemble the strategies outlined herein.5
1) Source: Bloomberg data.
2) Source: Bloomberg data.
3) Source: Bloomberg data.
4) Source: Bloomberg data.
5) Market Returns reference the following indices: Large Cap – S&P 500, Mid Cap Growth – Russell Midcap growth, Mid Cap Value – Russell Midcap Value, Small Cap – Russell 2000, Developed – MSCI EAFE, Emerging – MSCI Emerging Markets, Aggregate – Bloomberg US Aggregate, High Yield – Bloomberg High Yield
OAI01613