

Key Events: Elevated inflation, positive growth signals
This week’s inflation data came in hot, with core CPI and PPI both reflecting higher energy-driven readings.
Earnings season offered a constructive counter-narrative, as first quarter revenue growth is the highest it’s been since the second quarter of 20221. Retail sales and industrial production grew, signaling resilient underlying economic strength.
Market Review: Inflation fears lead to bond losses
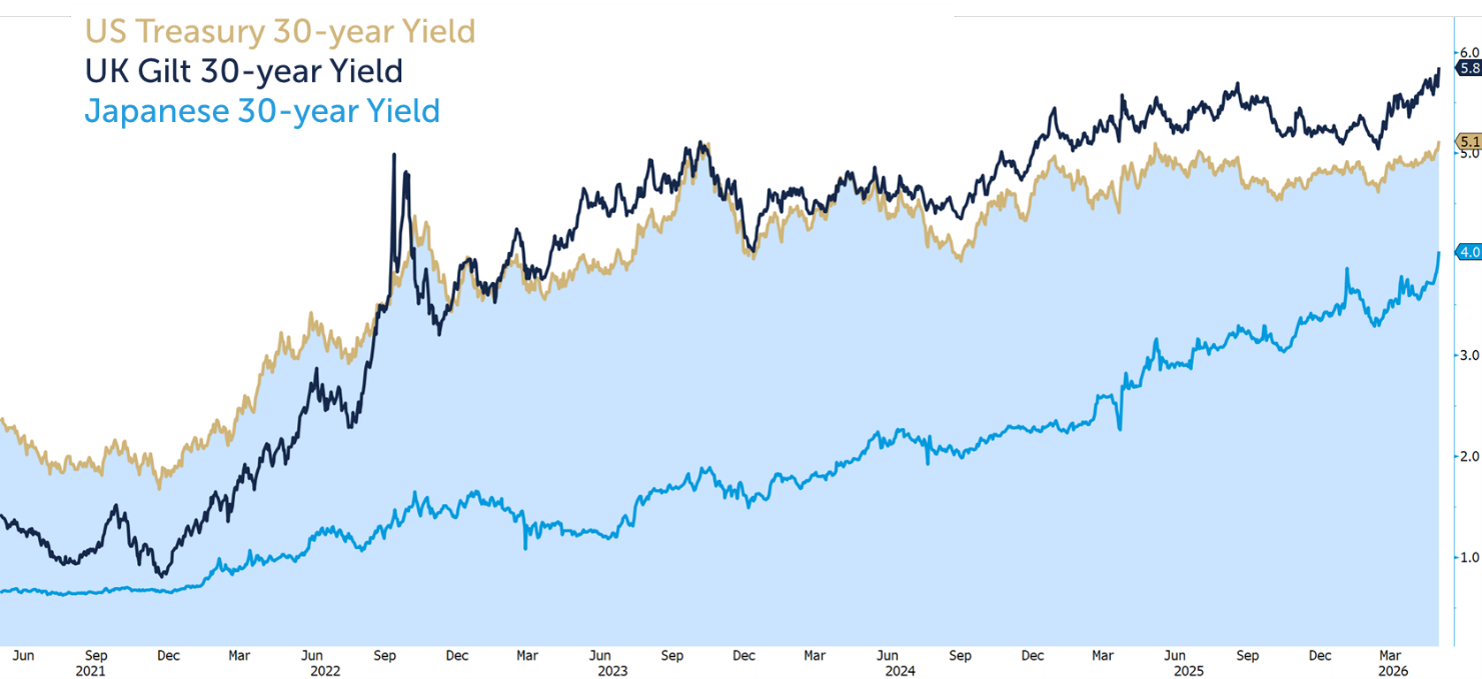
Global bond yields hit new highs this week (See chart below) reflecting worries over higher inflation.
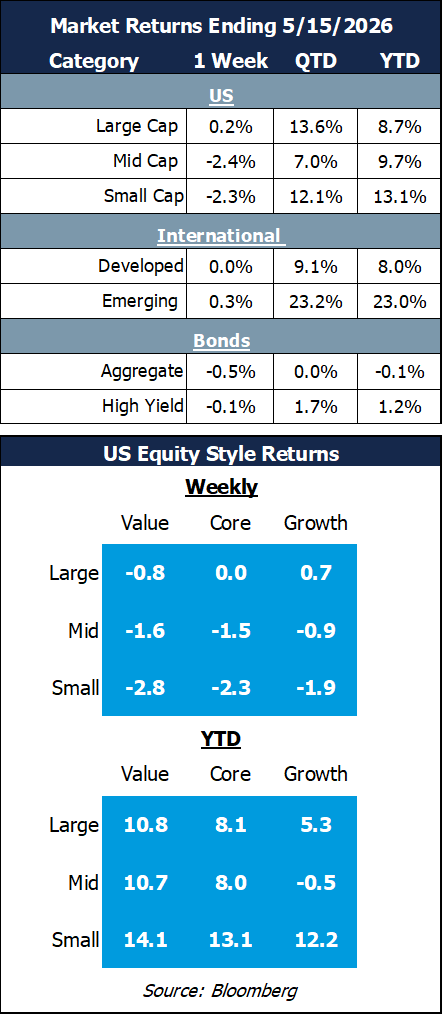
This caused a pause in the sharp second quarter stock rally. Large cap and international stocks managed to hold gains for the week, but US small and midcap stocks dropped given their higher sensitivity to bond yields.
Outlook: Risk times require a solid plan
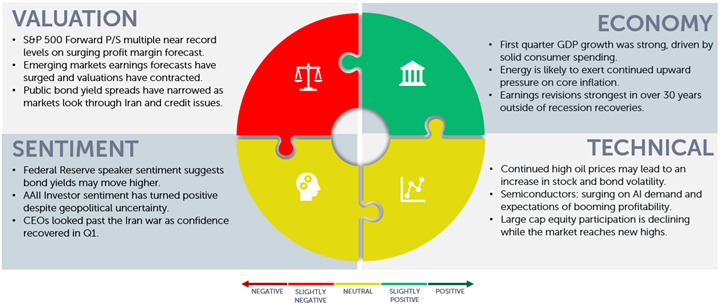
In the wake of the Trump tariff announcements a year ago, we discussed that the market might rise as long as things weren’t as bad as feared. Today’s market setup is the opposite – stocks have risen sharply and are arguably priced for perfection.
Several sources of instability could lead to a pullback:
-
-
The market is highly concentrated in a few names
-
Valuations are stretched across many investments
-
The war in Iran could drag on longer than expected
- A new Federal Reserve Chair adds policy uncertainty
-
These risks persist even as the market sets new highs on an almost daily basis. We raise them not to cause fear, but to remind investors that short-term losses are normal. Our models are broadly diversified, offering solid opportunities to protect capital and participate in gains. We encourage investors to have plan; maintain a diversified portfolio which allows you to stick with your plan if – when – the market throws you a curve ball.
Global bond yields spike on inflation concerns2
OneAscent Navigator Outlook: May 2026
This material is intended to be educational in nature , and not as a recommendation of any particular strategy, approach, product or concept for any particular advisor or client. These materials are not intended as any form of substitute for individualized investment advice. The discussion is general in nature, and therefore not intended to recommend or endorse any asset class, security, or technical aspect of any security for the purpose of allowing a reader to use the approach on their own. Before participating in any investment program or making any investment, clients as well as all other readers are encouraged to consult with their own professional advisers, including investment advisers and tax advisors. OneAscent can assist in determining a suitable investment approach for a given individual, which may or may not closely resemble the strategies outlined herein.7
2) Source: FactSet S&P 500 Reporting Highest Revenue Growth Since 2022
1) Source: Bloomberg
2) Market Returns reference the following indices: Large Cap – S&P 500, Mid Cap Growth – Russell Midcap growth, Mid Cap Value – Russell Midcap Value, Small Cap – Russell 2000, Developed – MSCI EAFE, Emerging – MSCI Emerging Markets, Aggregate – Bloomberg US Aggregate, High Yield – Bloomberg High Yield
OAI01530