

Key Events: Jobs growth fine and earnings shine
Non-farm payrolls increased by 115k in April, besting the consensus forecast of 65k.1 The unemployment rate held steady at 4.3%. In addition, continuing unemployment claims were less than expected and remain very low in a historical context, suggesting a firm labor market.
Earnings continued to come in well above expectations. First quarter earnings growth has been stellar results and looks to be on track to deliver roughly 27% growth, more than double the preseason forecast.2
Market Review: Torrid equity rally continued its surge
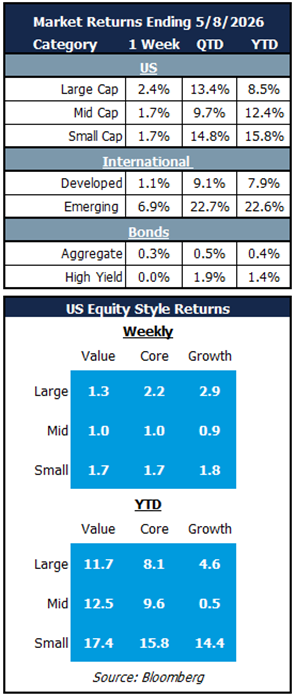
The S&P 500 notched its sixth-straight week of gains and closed at a new high on Friday.3 Information technology led the charge with a 7.0% gain for the week.4 Demand for AI hardware is outstripping supply, and it is overwhelming headline concerns over the war in the Middle East and associated volatility in oil markets.
Bond yields fell for the week but remain roughly 40 basis points higher than the onset of war.
Outlook: AI capital spending driving narrow rally
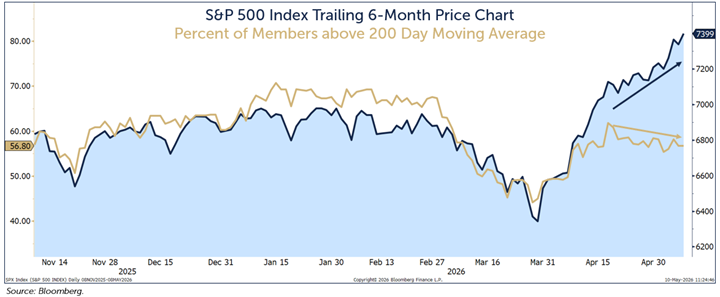
The S&P 500 has now rallied 16% since the low point at the end of March. Only 10 stocks have accounted for nearly 70% of the rally.5 While the list includes many of the original Magnificent 7 constituents, it also includes Avago, Intel, Micron, AMD and SanDisk. Collectively, these companies supply the hyperscalers the semiconductor chips and components that comprise data center servers.
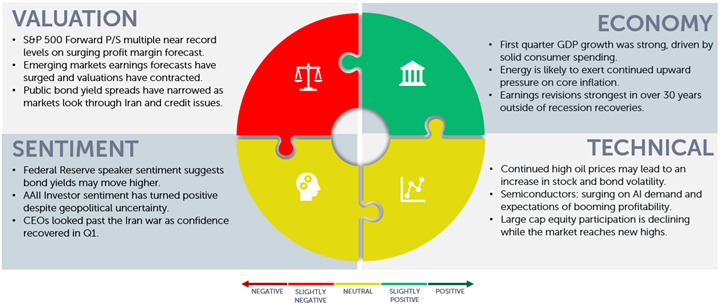
Earnings results from the 5 major hyperscalers highlighted an increase in capital spending plans for 2026, now exceeding $700 billion, an increase of more than $300 billion above 2025 spending.6 This aggressive growth in spending is also reflected in the results of the suppliers to the data center build-out mentioned previously and it is driving impressive earnings growth.
Rising profitability and accelerating growth are proving to be a potent mix, but these factors can also push valuations and expectations to unsustainable levels. Narrow leadership can be an early warning sign that conditions are getting tougher to maintain.
The last three weeks of market gains have been accompanied by narrowing breadth as shown in the chart below. The benefits of diversification often go dormant during periods of extreme concentration. Ironically, divergences that feature narrow leadership tend to offer opportunities to effectively rebalance portfolios to align with their long-term goals and objectives. We would advise investors to resist the urge to chase highflyers and embrace the principles of diversification.
Equity rally looking increasingly narrow as breadth weakens
OneAscent Navigator Outlook: May 2026
This material is intended to be educational in nature , and not as a recommendation of any particular strategy, approach, product or concept for any particular advisor or client. These materials are not intended as any form of substitute for individualized investment advice. The discussion is general in nature, and therefore not intended to recommend or endorse any asset class, security, or technical aspect of any security for the purpose of allowing a reader to use the approach on their own. Before participating in any investment program or making any investment, clients as well as all other readers are encouraged to consult with their own professional advisers, including investment advisers and tax advisors. OneAscent can assist in determining a suitable investment approach for a given individual, which may or may not closely resemble the strategies outlined herein.7
1) Source: Bloomberg story, “Hot Hiring + Rise in Unemployment = High Breakeven” by Anna Wong, dated 5/8/2026.
2) Source: Bloomberg BI – 1Q26 S&P 500 Earnings Tracker: Week4, by Wendy Soong and Nathaniel Welnhofer, dated 5/11/2026.
3) Source: Bloomberg data.
4) Source: Bloomberg data.
5) Source: Negligible Capital as shown in Syz weekly dated 5/9/2026.
6) Source: “Quarter Days and the Economic Outlook”, David Kelly of JP Morgan, May 4, 2026.
7) Market Returns reference the following indices: Large Cap – S&P 500, Mid Cap Growth – Russell Midcap growth, Mid Cap Value – Russell Midcap Value, Small Cap – Russell 2000, Developed – MSCI EAFE, Emerging – MSCI Emerging Markets, Aggregate – Bloomberg US Aggregate, High Yield – Bloomberg High Yield
OAI01527