

Key Events: Iran further disrupts energy, economy
Missile and drone attacks in the Persian Gulf escalated amid mixed signals from U.S. leadership about whether operations may soon wind down.
The Federal Reserve kept interest rates unchanged for a second consecutive meeting as the conflict-driven surge in oil prices further complicates the inflation outlook; policy makers expect one rate cut this year.
Market Review: Risk-off sentiment continues
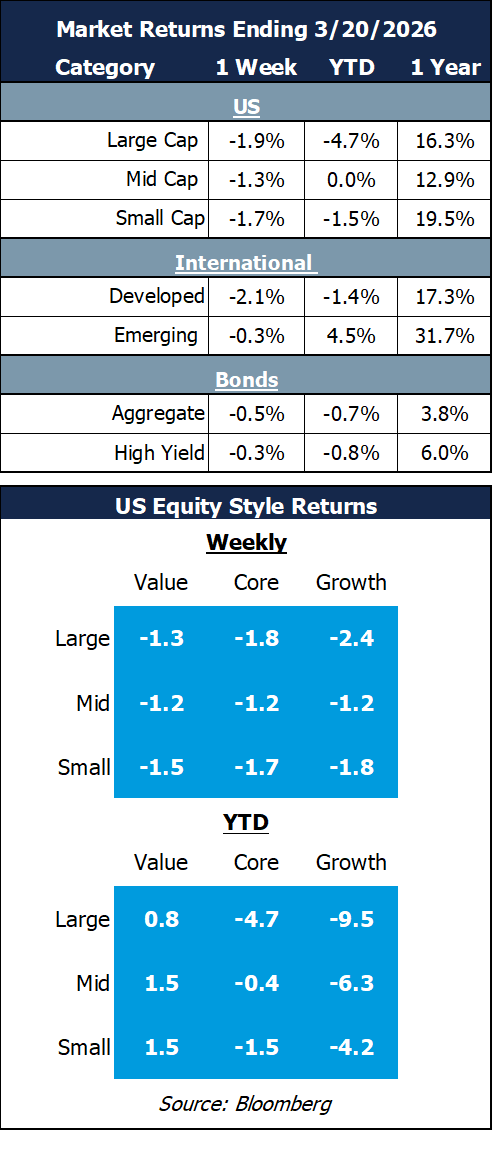
US stocks continued their selloff, with the S&P 500 reaching a 4.7% loss for the year. Bonds decline as markets now price in no rate cuts in 2026, in contrast to Fed expectations of one further rate cut.
Markets were shaken by sharp swings in energy and precious metals prices as traders weighed inflationary impacts of the conflict against steady U.S. growth.
Outlook: Maintaining a long-term perspective
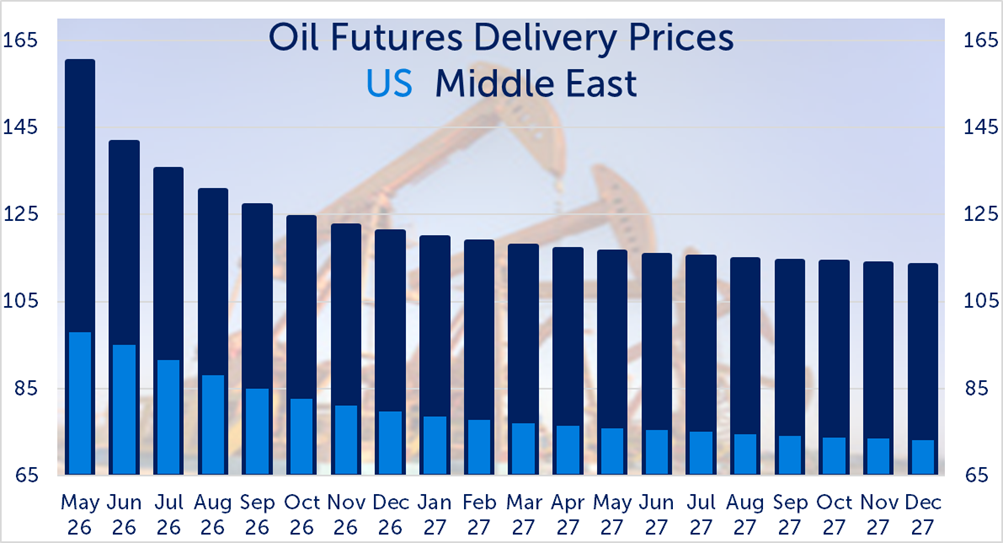
This week’s surge in Brent crude – as Iran’s closure of the Strait of Hormuz disrupts supply – has intensified the energy shock, but futures curves imply that markets expect partial normalization within the next several months. Additionally, as shown below, oil prices for delivery in the US – now a net exporter of oil- are far lower than for delivery in the middle east,1 and the market anticipates an end to the conflict as US delivery prices a year out are approaching their pre-war levels.
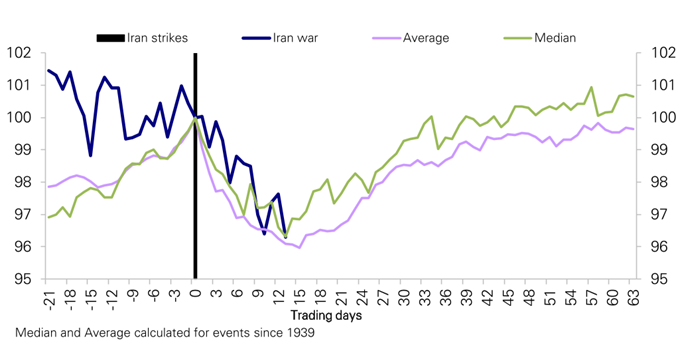
Federal Reserve policymakers acknowledge that the spike in oil prices is adding uncertainty to the inflation path even as they maintain expectations for one rate cut this year. The second chart below suggests this uncertainty will resolve in short order.2
Despite heightened volatility, equity markets remain resilient as investors weigh near‑term energy pressures against steady U.S. growth and the potential for a sharp rebound in risk assets should geopolitical tensions ease. We encourage investors to maintain focus on your long-term plan, not short-term market movements.
Oil futures are not anticipating extended disruption
S&P500 recoveries from major geopolitical events since 1939
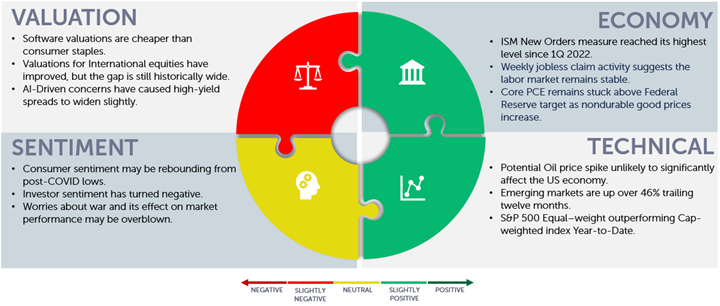
OneAscent Navigator Outlook: March 2026
This material is intended to be educational in nature , and not as a recommendation of any particular strategy, approach, product or concept for any particular advisor or client. These materials are not intended as any form of substitute for individualized investment advice. The discussion is general in nature, and therefore not intended to recommend or endorse any asset class, security, or technical aspect of any security for the purpose of allowing a reader to use the approach on their own. Before participating in any investment program or making any investment, clients as well as all other readers are encouraged to consult with their own professional advisers, including investment advisers and tax advisors. OneAscent can assist in determining a suitable investment approach for a given individual, which may or may not closely resemble the strategies outlined herein.
1 Source: Bloomberg – US Delivery is the West Texas Intermediate futures price. Middle East delivery is the Oman delivery price. WTI was priced at $67 on February 28
2 Source: Deutsche Bank Thematic Research: DB CoTD: Approaching the moment of historical truth… – Home
3 Market Returns reference the following indices: Large Cap – S&P 500, Mid Cap Growth – Russell Midcap growth, Mid Cap Value – Russell Midcap Value, Small Cap – Russell 2000, Developed – MSCI EAFE, Emerging – MSCI Emerging Markets, Aggregate – Bloomberg US Aggregate, High Yield – Bloomberg High Yield
OAI01483