

Key Events: Interim Iran deal looks increasingly likely
The Trump administration indicated on Friday afternoon that there was an 80-85% chance that an agreement gets signed soon between the US and Iran1. An interim peace deal would be expected to reopen the Strait of Hormuz and end Iran’s nuclear ambitions.
After threatening to bomb Iran again, a change in tone from President Trump mid-day Thursday gave global equities a lift that carried through Friday’s close.
Market Review: Equities advance on dual ‘deal hopes’
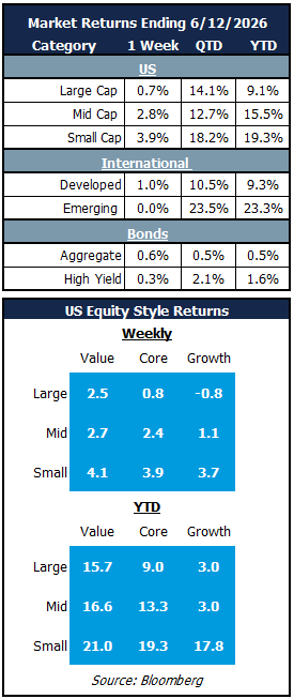
Global equities recovered nicely to end the week on a high note following a difficult start to the month. There were two types of deal hopes that marked the week: the hope for an Iran deal to relieve pressure on energy supplies and the public offering of SpaceX (SPCX). Both provided a positive backdrop for global equities.
Small and mid-cap stocks led the advance for equities and treasury yields fell for the week, lifting bonds as well.
Outlook: Significance of equity issuance beyond SPCX
It is fitting that Toy Story V is hitting theatres this week as the IPO that promises to unleash infinite opportunities beyond our terrestrial world just hit the markets. The focus on SpaceX has been otherworldly of late, but the significance of its public debut only represents a slice of new equity issuance landing over the coming months.
We have already absorbed a massive offering from Google (north of $80 billion raised) and a smaller $7 billion offering from Super-Micro Computer. Upcoming offerings from Anthropic, OpenAI and a secondary from META are expected to collect well above $200 billion from investors. Add it all up and this bumper crop of issuance could exceed $400 billion from this group alone.2 Companies are issuing equity for the following reasons: 1) the need for capital to support growth initiatives; 2) capitalize on the favorable pricing environment (high valuations) and extremely high investor enthusiasm; and 3) offer some of their early investors an opportunity to reduce and diversify their exposure.
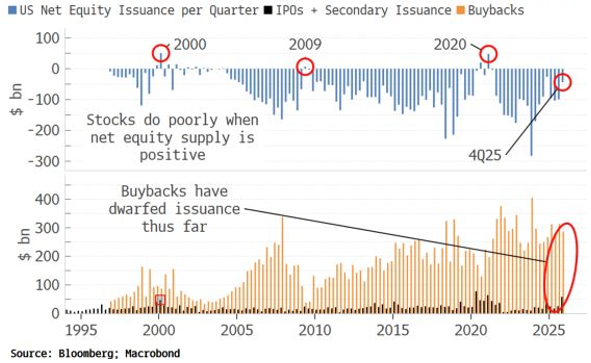
The historical record since the turn of the century indicates periods of high equity issuance are often associated with poorly performing equity markets as shown in the chart below by Simon White.3 The capex demands for the AI buildout are absorbing so much cash flow that companies are being forced to adjust their capital allocation strategies. The changing environment has led to beneficial performance for diversified portfolios as the Mag-7 has lagged the broader market thus far in 2026. We would counsel advisors to continue leaning into the principles of disciplined rebalancing and diversification to capture opportunities beyond the overhyped and overvalued.
Low Issuance and Buybacks Have Kept Net Equity Supply Negative4
OneAscent Navigator Outlook: June 2026
This material is intended to be educational in nature , and not as a recommendation of any particular strategy, approach, product or concept for any particular advisor or client. These materials are not intended as any form of substitute for individualized investment advice. The discussion is general in nature, and therefore not intended to recommend or endorse any asset class, security, or technical aspect of any security for the purpose of allowing a reader to use the approach on their own. Before participating in any investment program or making any investment, clients as well as all other readers are encouraged to consult with their own professional advisers, including investment advisers and tax advisors. OneAscent can assist in determining a suitable investment approach for a given individual, which may or may not closely resemble the strategies outlined herein.5
1) Source: Bloomberg story, “US Vows Interim Iran Deal Will Reopen Hormuz, End Nuclear Threat” by Hadriana Lowenkron, Josh Wingrove and Eric Martin, dated 6/11/2026.
2) Source: Based on a range of estimates from multiple sources referencing IPO and secondary share offerings of Anthropic, OpenAI and META.
3) Source: Bloomberg article “The Game Is Up When Firms Start Selling Their Stock”, by Simon White dated 6/9/2026.
4) Source: Chart from Simon White article “The Game Is Up When Firms Start Selling Their Stock” dated 6/9/2026.
5) Market Returns reference the following indices: Large Cap – S&P 500, Mid Cap Growth – Russell Midcap growth, Mid Cap Value – Russell Midcap Value, Small Cap – Russell 2000, Developed – MSCI EAFE, Emerging – MSCI Emerging Markets, Aggregate – Bloomberg US Aggregate, High Yield – Bloomberg High Yield
OAI01552