

Key Events: ‘Strait’ talks on-again, off-again
Negotiations to end the war and open The Strait of Hormuz have stalled. President Trump delayed hope of any near term resolution on Saturday when he posted that he “just cancelled the trip of my representatives going to Islamabad, Pakistan, to meet with the Iranians”.1 While the ceasefire is temporarily extended, the situation remains tenuous at best and firming oil prices continue to weigh on the global economy.
Market Review: Stocks at new highs in narrow advance
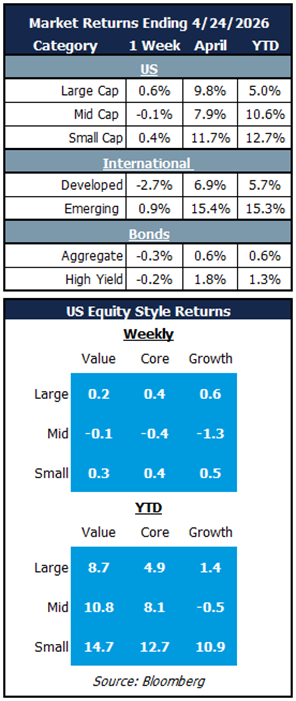
The S&P 500 edged out a new high last week with a solid finish on Friday. Semiconductor stocks were by far the week’s biggest gainers as the Philadelphia Semiconductor Index tacked on 10% for the week.2 Yet, the S&P equal-weight index retreated for the week, signaling narrow market performance has gripped the equity market once again.
Outlook: K-shape relationships pervading the markets
The K-shape divergence has frequently been used by economists in recent years to illustrate differences in demographics, income inequality and more recently the gap between a resilient stock market and declining consumer confidence. Over the past 6 months, this pattern shape has become unambiguously evident within the technology sector.
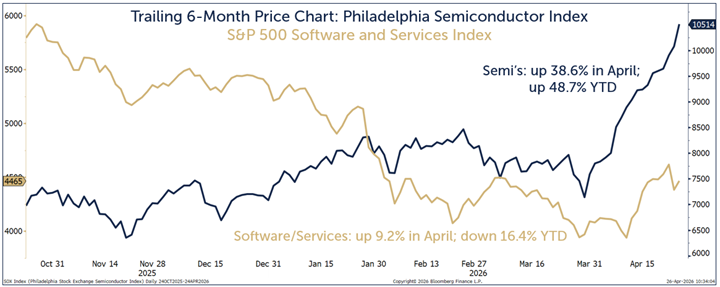
The powerful rally in the Philadelphia Semiconductor Index highlights the strength of the upper arm of the ‘K’. Strong results from Texas Instruments and an improved outlook from Intel propelled a ‘semi-surge’ that has the sector up more than 38% this month alone. This momentum is supported by continued robust data-center capex fueling the AI expansion.
In contrast, the lower arm of the K-shape represents growing risks to software and technology service providers. Rapid AI advances are creating a very real threat of disintermediation for many incumbents.
The chart below shows recent performance but does not reflect valuations for these technology index segments. Semiconductors now trade at a rather rich forward P/E ratio of 58x (Bloomberg estimates), while software’s forward P/E has fallen more than 35% to a historically attractive 24x. These valuation dislocations often create opportunity. Some software companies may come under threat, but others are poised to harness AI to strengthen their position and create substantial value for investors.
The current pace and scale of the AI expansion are staggering, but its ultimate impacts and long-term outcomes are unknown and challenging to predict. We continue to stress diversification across sectors, styles, market capitalization and geography. Within major sectors like technology, diversification is paramount to capture emerging opportunities as they unfold while moderating exposure to elevated valuations in the most overheated segments.
K-shape dividing the broader technology sector
OneAscent Navigator Outlook: April 2026
This material is intended to be educational in nature , and not as a recommendation of any particular strategy, approach, product or concept for any particular advisor or client. These materials are not intended as any form of substitute for individualized investment advice. The discussion is general in nature, and therefore not intended to recommend or endorse any asset class, security, or technical aspect of any security for the purpose of allowing a reader to use the approach on their own. Before participating in any investment program or making any investment, clients as well as all other readers are encouraged to consult with their own professional advisers, including investment advisers and tax advisors. OneAscent can assist in determining a suitable investment approach for a given individual, which may or may not closely resemble the strategies outlined herein.
1) Source: The Hill article, “Trump scraps latest peace talks after Iranian officials depart Pakistan” dated April 25, 2026.
2) Source: Bloomberg data.
3) Market Returns reference the following indices: Large Cap – S&P 500, Mid Cap Growth – Russell Midcap growth, Mid Cap Value – Russell Midcap Value, Small Cap – Russell 2000, Developed – MSCI EAFE, Emerging – MSCI Emerging Markets, Aggregate – Bloomberg US Aggregate, High Yield – Bloomberg High Yield
OAI01502