

Key Events: Oil prices plunge on news that the Strait of Hormuz is “completely open”
Oil prices dropped sharply on Friday morning after Iran’s Foreign Minister Abbas Aragchi posted a comment on X that the Strait of Hormuz is “completely open” for commercial shipping.1 The reopening turned out to be rather brief as Iran reimposed restrictions. Negotiations are set to continue in the week ahead, but chaos over the Strait of Hormuz could reverse the recent reduction in equity volatility and oil prices.
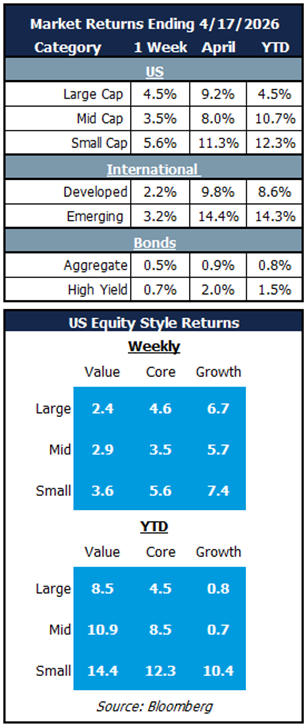
Market Review: Stocks surge to new all-time highs
Equities closed at new record highs on three straight days to end the week as hope for the end of war continued to build. The oil price decline on Friday took pressure off inflation forecasts, which could give the Federal Reserve more flexibility to cut rates as the year progresses.
Earnings season kicked off with some healthy reports from the banks, but markets are likely to remain on edge until a peaceful resolution becomes clear.
Outlook: Markets discounting an improved outlook
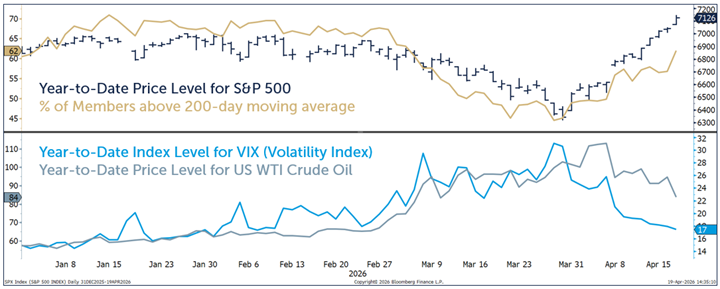
The superlatives to describe the recent rally are nothing short of breathtaking. The S&P 500 displayed three straight weeks of gains of 3% or more – the last 3 times that happened – June 2020, September 1982 and September 19402. The Nasdaq posted its 13th consecutive gain and its longest winning streak since 20093. In addition, the S&P posted its second fastest rally from oversold to overbought conditions since 19504 and the VIX fell from 31 to 17 in the last 3 weeks.
Critical observers could have cited breadth as non-confirming, but the percentage of S&P 500 members trading above the 200-day moving average jumped on Friday along with the decline in the oil price as depicted in the chart below. Recoveries to all-time highs often coincide with an improving technical backdrop and historical comparisons suggest more gains are likely to follow in the months ahead.
While these conditions emerged at the close of last week, developments over the weekend have thrown the idea of continued peaceful negotiations into a tailspin. Tensions have flared over the US seizure of an Iranian warship, so the chaos in the Middle East appears to be far from any near term conclusion5. This only reinforces the importance of retaining proper focus on the principles guiding strategic portfolio allocation: long-term objectives coupled with diversification by sector, style, market capitalization and geography.
Stocks surged while volatility and oil prices declined on continued progress toward de-escalation in war with Iran
OneAscent Navigator Outlook: April 2026
This material is intended to be educational in nature , and not as a recommendation of any particular strategy, approach, product or concept for any particular advisor or client. These materials are not intended as any form of substitute for individualized investment advice. The discussion is general in nature, and therefore not intended to recommend or endorse any asset class, security, or technical aspect of any security for the purpose of allowing a reader to use the approach on their own. Before participating in any investment program or making any investment, clients as well as all other readers are encouraged to consult with their own professional advisers, including investment advisers and tax advisors. OneAscent can assist in determining a suitable investment approach for a given individual, which may or may not closely resemble the strategies outlined herein.
1) Source: Bloomberg story, “Oil and Gas Plunge on Hormuz Opening, Hope for End of War”, dated April 17, 2026.
2) Source: Syz weekly dated April 18, 2026, with data and credits from www.zerohedge.com and Bloomberg.
3) Source: Lance Roberts article “Short Covering Rally Or Is The Bull Market Back?”, dated April 19, 2026.
4) Source: Bloomberg graphic “S&P 500 Fast Paced Weakness to Strength Rallies”.
5) Source: Bloomberg article “US Seizes Iranian Ship in Blockade, Casting Doubts on Peace Talks”.
6) Market Returns reference the following indices: Large Cap – S&P 500, Mid Cap Growth – Russell Midcap growth, Mid Cap Value – Russell Midcap Value, Small Cap – Russell 2000, Developed – MSCI EAFE, Emerging – MSCI Emerging Markets, Aggregate – Bloomberg US Aggregate, High Yield – Bloomberg High Yield
OAI01495