

Key Events: De-escalation signals
Macro risk sentiment pivoted sharply this week following a surprise ceasefire announcement from Trump which echoed last year’s abrupt tariff pause: The unilateral announcement did not resolve underlying tensions, but gave respite, however brief, to an unstable situation. In both cases, the proclamation lowered risk premiums, yet the durability of the current move remains openly debated, reflecting the complicated nature of middle eastern geopolitics.
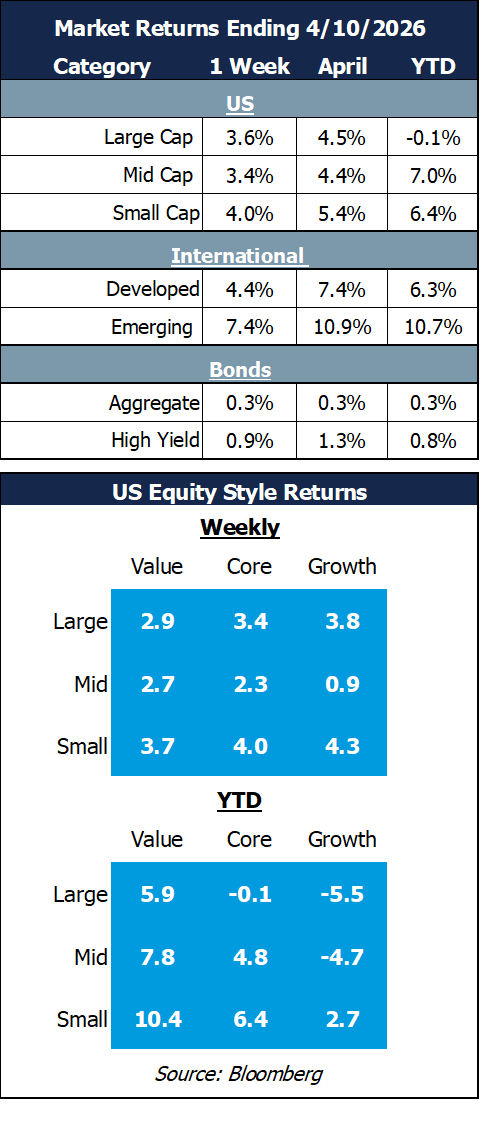
Market Review: Lead to a sharp stock rally
The cease fire prompted a swift recalibration across assets. Equities responded to the sudden reduction in worst‑case assumptions, allowing riskier emerging markets and small caps to lead again this week.
Despite positive earnings revisions, markets remain fragile, as oil charged higher again as cease-fire talks over the weekend were suspended.
Outlook: Oil and the middle east
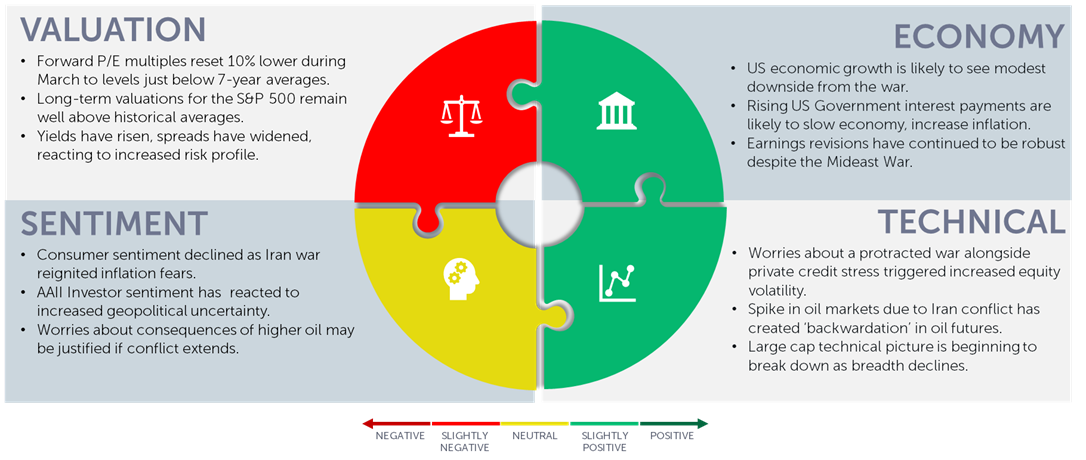
Recent headlines have elevated near‑term uncertainty, particularly around reported U.S. actions affecting the Strait of Hormuz. These developments have supported energy prices and revived tail‑risk concerns around inflation. At the same time, equity fundamentals remain firm, with positive earnings revisions pointing to underlying economic resilience. Investors are also weighing the potential for private‑credit stress to migrate into public markets, alongside a pullback in technology shares that reflects positioning and valuation sensitivities rather than a broad deterioration in fundamentals.
While geopolitical and financial crosscurrents may drive near-term volatility, the earnings and economic backdrop remains constructive. We continue to encourage investors to recognize near‑term risks without overreacting to them. Staying focused on long‑term objectives and portfolio alignment—rather than headline‑driven adjustments—remains essential when uncertainty rises and narratives shift faster than fundamentals.
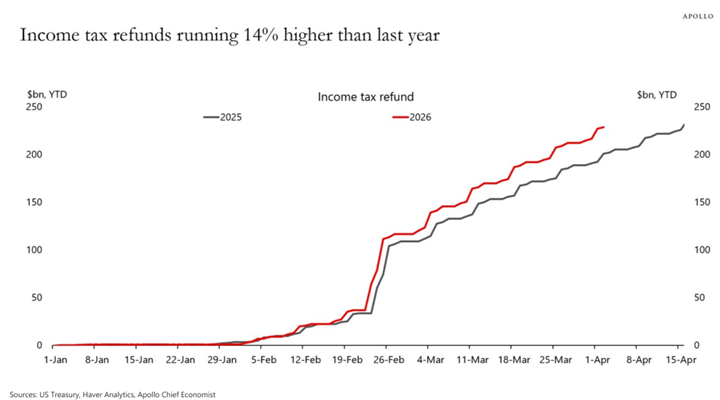
Some good news during tax-filing week
OneAscent Navigator Outlook: April 2026
This material is intended to be educational in nature , and not as a recommendation of any particular strategy, approach, product or concept for any particular advisor or client. These materials are not intended as any form of substitute for individualized investment advice. The discussion is general in nature, and therefore not intended to recommend or endorse any asset class, security, or technical aspect of any security for the purpose of allowing a reader to use the approach on their own. Before participating in any investment program or making any investment, clients as well as all other readers are encouraged to consult with their own professional advisers, including investment advisers and tax advisors. OneAscent can assist in determining a suitable investment approach for a given individual, which may or may not closely resemble the strategies outlined herein.
1) Market Returns reference the following indices: Large Cap – S&P 500, Mid Cap Growth – Russell Midcap growth, Mid Cap Value – Russell Midcap Value, Small Cap – Russell 2000, Developed – MSCI EAFE, Emerging – MSCI Emerging Markets, Aggregate – Bloomberg US Aggregate, High Yield – Bloomberg High Yield
OAI01493