

Navigating June’s converging narratives
June compressed an unusual amount of complexity into a single month. Strait of Hormuz traffic remained well below pre-war levels, and what the IEA characterized as the largest supply disruption in the history of the global oil market continued feeding an inflation impulse markets could not look past. That energy-driven inflation, in turn, constrained the new Fed and defined the arc of the month.
Clear hawkishness defined Kevin Warsh’s first FOMC meeting in June. The Fed held rates steady, eliminated forward guidance and shifted the dot plot materially: nine of eighteen voting members now project a hike before year-end.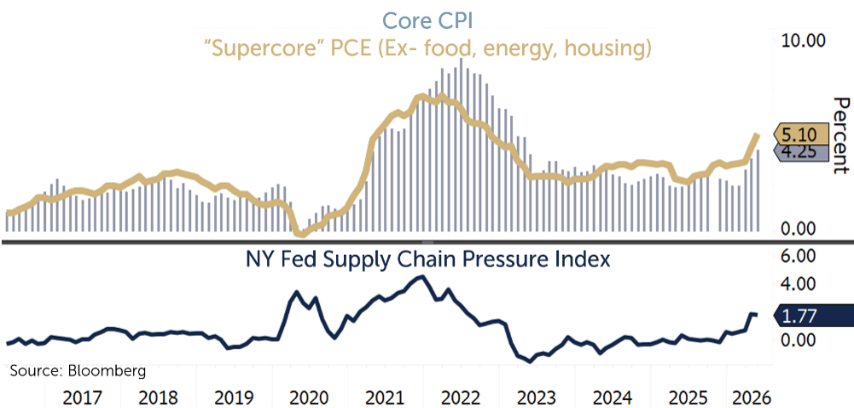 May’s inflation report confirmed the Fed’s view. Markets that began the year pricing one to two cuts are now debating the timing of hikes.
SpaceX’s IPO was the month’s defining risk-asset event, and ultimately a parable about sentiment’s fragility. Priced at $135, the offering raised $75 billion and briefly made SpaceX the fourth-most-valuable public company in the world, with shares peaking near $225. A 16% single-session decline erased most of those gains, leaving the stock near $153 at month-end—above its offering price, but well off the highs. Animal spirits around transformational narratives still command capital; the market’s willingness to sustain any premium is another matter, particularly when the macro backdrop is tightening.
Equity returns were mixed in June as this volatility rippled through growth names. AI capex remains a durable pillar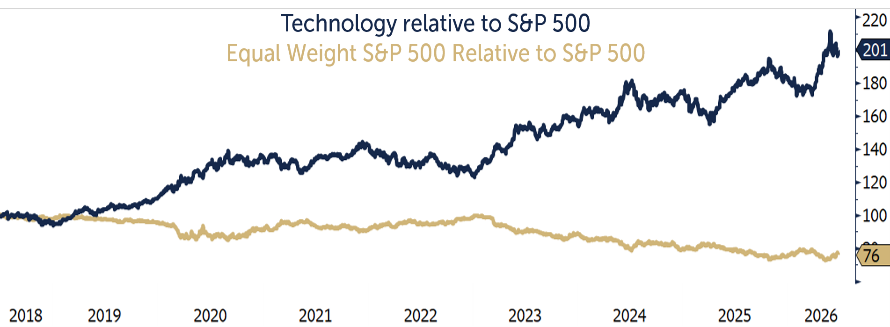 of the bull case but is increasingly in tension with a rate outlook that has pivoted from neutral as bond yields have increased during the first half of the year. That backdrop accelerated a broadening trend already quietly underway: technology’s multi-year outperformance reversed and equal-weight indices closed the gap on cap-weighted peers1. These are early innings, and a single month doesn’t make a regime change—but the valuation math is shifting, and June may mark the moment that rotation moved from tactical to structural.
June illustrated how forces that defined prior months can evolve. The Iran ceasefire that briefly lifted spirits gave way to a June defined by its economic aftershocks—energy prices that refuse to normalize, an inflation trajectory that has cornered the new Fed Chair, and a growth narrative turbulent enough to take SpaceX from historic euphoria to sharp correction in under three weeks. We will discuss how these threads connect to the second half of 2026 but first let’s review the details of June’s market performance.
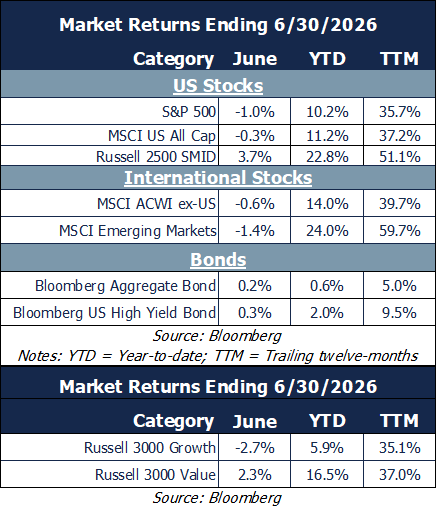
June Market Review
Markets were driven by changing narratives:
- Bonds settled into a new environment characterized by less Fed guidance amidst a resurgence of inflationary fears.
- Technology-driven stock markets retreated as SpaceX-driven hype dominated the headlines.
- Stock performance broadened under the surface; the equal weight S&P 500 was up 2.4% and value is significantly outpacing growth.
- U.S. small and mid‑cap stocks outpaced Large and international stocks due to lower technology exposure, despite higher sensitivity to interest rate changes.
Sector returns illustrate the changing narratives:
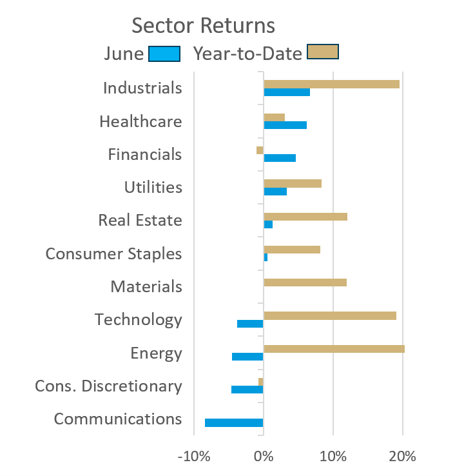
- Industrials stocks led the way in June and are near the top of the charts YTD as they benefit from the AI-driven data center buildout.
- Healthcare and Financials benefitted from the shift away from technology stocks.
- Technology, consumer discretionary and communications pulled back as the wind came out of the “mag-7” momentum.
- Energy fell in June on Iran progress, but remains the top sector on a YTD basis.
Our Navigator framework informs us of our outlook.
July 2026 Navigator Outlook
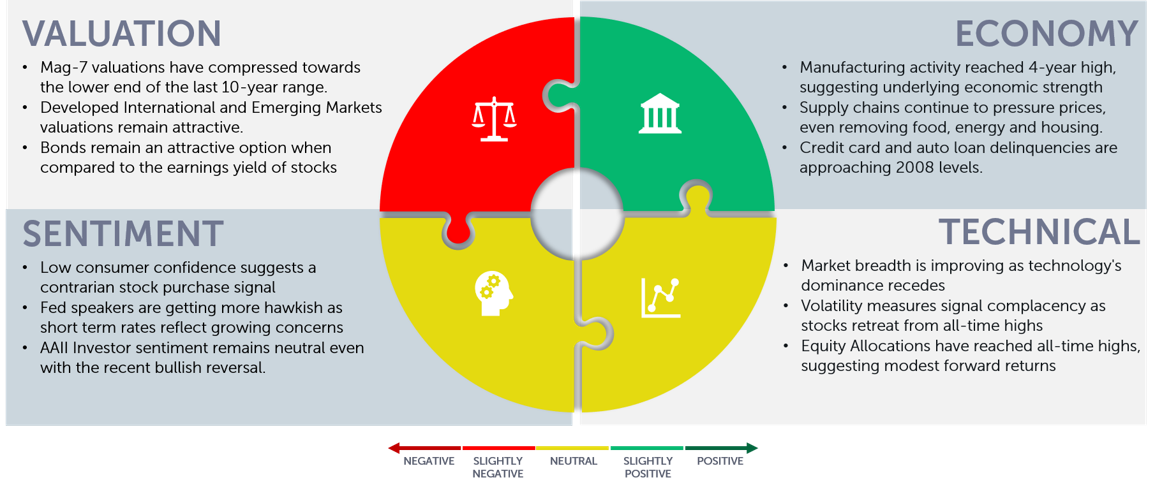
Economy: Manufacturing activity reached a 4-year high, suggesting underlying economic strength. Supply chains continue to pressure prices, even measures that remove volatile food, energy and housing. Credit card and auto loan delinquencies are approaching 2008 levels, reflecting the fragility and “K-shaped” nature of today’s economic growth.
Technicals: Market breadth is improving as technology’s dominance recedes. Volatility measures signal complacency as stock markets retreat from all-time highs. Meanwhile, Equity Allocations have reached all-time highs, suggesting modest forward returns.
Sentiment: Low consumer confidence suggests a contrarian stock purchase signal. Fed speakers are getting more hawkish as short term rates reflect growing concerns. AAII Investor sentiment remains neutral even with the recent bullish reversal.
Valuation: Mag-7 valuations have compressed towards the lower end of the last 10-year range. Developed International and Emerging Markets valuations remain attractive. Bonds remain an attractive option when compared to the earnings yield of stocks.
Outlook and Recommendations: Maintaining course through turbulent waters
Markets enter July with a strong first half behind them and more complexity ahead than the headline numbers suggest. The S&P 500 gained 9.6% through June, and small caps surged nearly 23%—their best first half of the year since 1991—but stocks retreated from all-time highs late in the month, and the confidence underlying that strength is more fragile than it appears. The U.S.–Iran framework signed in mid-June briefly sent oil sharply lower and stocks rallying, but renewed strikes in the final days of the month have strained the ceasefire and left the Strait of Hormuz reopening in doubt. Oil remains above pre-war levels, and inflation—which had been gradually moderating—reached a three-year high of 4.2% in May, complicating the Fed’s path and investors’ assumptions about the second half of the year.
The Fed transition is the dominant policy variable heading into July. Chair Warsh presided over his first FOMC meeting in June, a meeting marked by a shift towards potential hikes this year—a shift markets are still digesting. Fed rhetoric has turned more hawkish, and short-term rates have moved higher to reflect growing inflation concerns. The early months of any Fed leadership change tend to introduce a repricing of uncertainty—not because policy necessarily changes, but because the market’s confidence in its ability to predict policy does. That uncertainty is real, and may persist for some time.
The underlying economic picture, however, remains broadly constructive, if uneven. Manufacturing activity reached a four-year high in June, labor markets are holding up, and business investment—particularly in AI infrastructure—remains a durable tailwind. The SpaceX IPO was a defining moment for risk appetite in June, and its aftermath matters for the second half of the year. A stabilization of risk appetite would be favorable heading into earnings season. Large-cap earnings revisions have accelerated on strong AI-driven semiconductor demand, and the broadening of market participation beyond mega-cap technology continues to look structural rather than tactical: market breadth is improving as technology’s dominance recedes, and small-cap leadership in the first half underscores the shift. Still, there are cracks worth watching. Credit card and auto loan delinquencies are approaching levels last seen in 2008, and supply chains continue to pressure prices even excluding food, energy, and housing—a reminder that inflation is not solely an energy story.
Valuation and positioning tell a more cautionary story. Magnificent 7 valuations have compressed toward the low end of their ten-year range—weighed down by heavy capital spending and new equity supply—while developed international and emerging markets remain attractively valued with improving earnings trends. Bonds remain compelling relative to the earnings yield of stocks. At the same time, equity allocations have reached all-time highs, a condition historically associated with modest forward returns, and volatility measures signal complacency even as stocks sit below their highs. Low consumer confidence, a historically contrarian buy signal, leading to a mixed sentiment picture.
Inflation remains the variable most capable of disrupting an otherwise constructive backdrop. Oil prices are the transmission mechanism to watch—elevated energy costs feed into goods and services inflation, constrain consumer purchasing power, and make the Fed’s job harder. The longer the ceasefire remains fragile and Hormuz flows stay uncertain, the more likely elevated oil prices exert a sustained upward pull on inflation rather than a transitory one. That distinction matters enormously for how the Fed responds and how fixed income markets price the back half of 2026.
Overall, the investment landscape entering July is supportive but demands discipline. Fundamentals remain resilient, leadership is broadening, and valuations outside U.S. mega-cap continue to offer long-term opportunity. Our positioning reflects that balance.
Portfolio Construction and Positioning
Our Navigator process helps guide our portfolio construction, reflecting the broadly supportive economic outlook. Our portfolio is focused on the following:
- Mid-cap and international equities: These segments offer attractive valuations relative to U.S. large caps and provide long-term diversification benefits. The market is beginning to recognize these advantages.
- Balanced exposure across styles: We maintain a mix of growth and value stocks poised to benefit as broadening trends take hold.
- Fixed income remains compelling: Bond yields exceed the earnings yield of large-cap equities, and real (inflation-adjusted) yields are positive—supporting the case for continued fixed income exposure.
- Mortgage-backed securities: We see favorable risk-reward dynamics here as even a modest increase in pre-payments could be a catalyst. Corporate credit spreads remain narrow, limiting upside in riskier sectors of the bond market.
- Alternative investments: We continue to find meaningful opportunities in both non-correlated public strategies and private market investments which offer potentially higher returns than the public markets.
While the first half of the year has rewarded investors, we must remember that volatility is the price of participation in the markets. The case for staying invested in a diversified portfolio, focused on the fundamentals, remains intact. A broadly diversified portfolio offers the best chance at maintaining discipline in the face of potential short-term volatility. We counsel investors to remain invested, remain disciplined, and remain focused on their plan.
This material is intended to be educational in nature, and not as a recommendation of any particular strategy, approach, product or concept for any particular advisor or client. These materials are not intended as any form of substitute for individualized investment advice. The discussion is general in nature, and therefore not intended to recommend or endorse any asset class, security, or technical aspect of any security for the purpose of allowing a reader to use the approach on their own. Before participating in any investment program or making any investment, clients as well as all other readers are encouraged to consult with their own professional advisers, including investment advisers and tax advisors. OneAscent can assist in determining a suitable investment approach for a given individual, which may or may not closely resemble the strategies outlined herein.2
1) Source: Bloomberg
2) Source: Market Returns reference the following indices: Large Cap – S&P 500, Mid Cap Growth – Russell Midcap growth, Mid Cap Value – Russell Midcap Value, Small Cap – Russell 2000, Developed – MSCI EAFE, Emerging – MSCI Emerging Markets, Aggregate – Bloomberg US Aggregate, High Yield – Bloomberg High Yield
OAI01562